


Your Health Magazine Contributor
4201 Northview Drive
Suite 102
Bowie, MD 20716
More Health Insurance Articles
Do You Need a Super Top-Up If You Already Have Health Insurance?
Super Top-Up With Insurance? Beat the Renewal Premium Increase Every Year
A health insurance policy is a responsible first step, and most people feel settled once it is in place. However, a renewal premium increase every year can change how comfortable that decision feels. Your needs may also change as your family grows or your health priorities shift. In such cases, many policyholders ask whether their current cover is enough. A super top-up is one option worth understanding in detail.
This blog explains when a super top-up becomes useful, who may need it and how it supports your existing health insurance.
Why Does Renewal Premium Increase Every Year?
Your premium increases at renewal mainly because of medical inflation, your age and wider claim trends. This is why many policyholders see a renewal premium increase every year. Raising your base sum insured to keep pace can push the premium up further. A super top-up offers another route by adding cover above a chosen threshold.
Here are the common factors that can influence premium revisions:
- Medical inflation raises the cost of treatment, hospital stays, diagnostics, medicines and consultations.
- Your age moves you into a different risk bracket as the years pass.
- A higher sum insured generally leads to a higher premium.
- Claim trends and healthcare usage in your city or region may also play a role.
- Add-ons and riders attached to the policy can change the total premium.
Premium revisions remain subject to the insurer’s underwriting guidelines and regulatory norms.
How Does a Super Top-Up Plan Work?
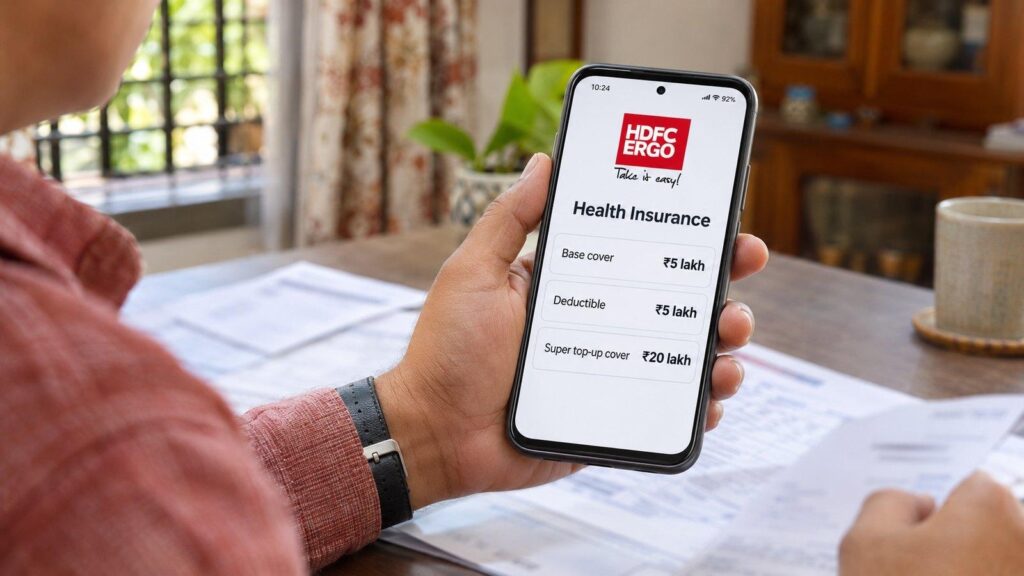
A super top-up pays once your medical expenses in a policy year cross a chosen deductible. Your base policy, employer cover or savings can meet the amount up to that limit. An aggregate deductible means that multiple claims in one policy year add up together. This makes the plan useful when a single illness or several smaller hospitalisations push expenses higher.
Actual claim settlement depends on the policy terms and conditions.
When Should You Consider a Super Top-Up?
Adding one may suit you in situations such as these:
- Your base sum insured feels limited compared with current hospital costs in your city.
- You wish to extend protection to your spouse, children, dependent parents and other eligible family members.
- You want a budget-friendly way to raise overall protection without replacing your existing plan.
- You expect higher medical needs because of age, family history, planned treatments or a chronic condition.
How Does It Compare with Raising Your Base Cover?
Many health insurance plans allow you to increase the sum insured at renewal. A super top-up works differently, so a side-by-side view helps. Here is how the two approaches compare:
| Aspect | Super top-up | Higher base sum insured |
| Claim payment | Begins after the deductible is met | Begins from the first eligible expense, as per policy terms |
| Premium approach | The deductible reduces insurer exposure, so cover can stay cost-effective | Premium rises along with the sum insured |
| Policy structure | Works alongside your current policy | Increases or replaces the current policy |
| Suited for | Larger medical needs | Routine and smaller hospital bills |
What Expenses Can a Super Top-Up Help Cover?
Once you reach your deductible, a super top-up helps with eligible medical expenses. The exact benefits vary from plan to plan. Here is what some of the popular plans include:
- Hospital stays when the admission is medically necessary.
- Consultations and diagnostic tests before you are admitted.
- Follow-up visits and medicines after you are discharged.
- Day care procedures that do not need an overnight stay.
- Emergency ambulance charges.
How Do Claims Work With Two Policies?
When you hold a base policy and a super top-up, a single hospitalisation can involve both. Your base policy usually responds first. The super top-up then supports eligible expenses beyond the deductible. A few simple steps can keep the process smooth:
- Tell your insurer about the hospitalisation as early as you can.
- Keep your discharge summary, bills, prescriptions and reports ready.
- Share your base policy details with the super top-up insurer.
- Send documents to both insurers within the stated timelines.
Final Thoughts
A super top-up extends your existing cover rather than replacing it. It can help you handle larger medical bills, and you may not need to raise your base policy as often. Look at your current sum insured, your family’s needs, your city of residence and the deductible you can manage. Compare policy terms carefully before you choose one. If you need clarity on suitability, an insurance advisor can help.
References
- https://www.hdfcergo.com/health-insurance/my-health-medisure-super-top-up-insurance
- https://www.cholainsurance.com/knowledge-center/health-insurance/why-health-insurance-premiums-go-up-every-year-and-what-you-can-do-about-it
Other Articles You May Find of Interest...
- Do You Need a Super Top-Up If You Already Have Health Insurance?
- Why Working With a Local Medicare Broker Beats Choosing a Plan Alone
- How to Choose Private Health Insurance in Canada Based on Your Healthcare Needs
- Why Young Adults Should Think about Health Insurance before a Medical Emergency
- Marketplace vs. Off-Marketplace Health Insurance in Texas: What Factors Should Buyers Consider?
- Are You Paying Too Much for Medicare Coverage? What to Review Each Year
- Physio, Chiro and Massage: How Australia Insures the Hands-On Care Most US Plans Leave Out